News - ملاك المنازل المسنون يواجهون اتجاهات الرهن العقاري المتزايدة
Business Strategy
ملاك المنازل المسنون يواجهون اتجاهات الرهن العقاري المتزايدة
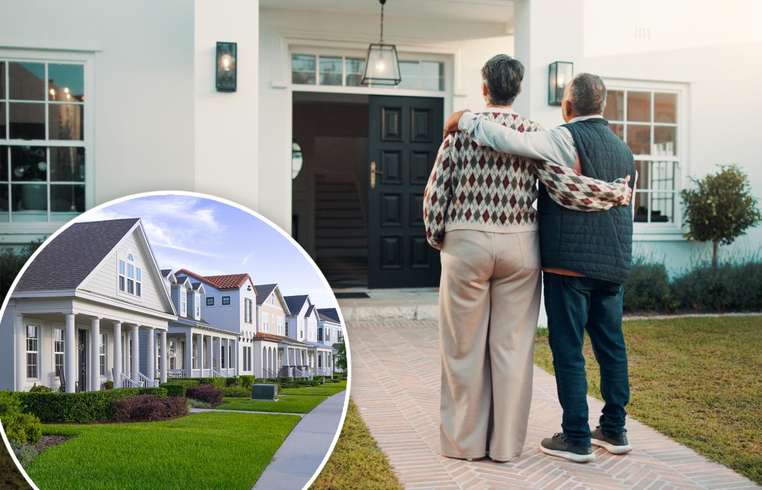
In a shifting landscape of homeownership in America, an increasing number of elderly homeowners are continuing to bear the burden of mortgage payments, a trend that contrasts with the overall rise in mortgage-free properties across the nation. According to a recent analysis by Realtor.com, utilizing US Census Bureau data, a significant rise was observed in mortgage-free ownership—41% of owner-occupied homes were owned outright by 2025, a notable increase from 32.8% in 2010. However, this positive trend is not reflected among Americans aged 75 and older, where the presence of mortgage debt has markedly risen. In the last 15 years, from 2010 to 2025, the number of senior homeowners with active mortgages has surged from 1.79 million to 3.93 million. While the overall aging population has grown, the pattern of purchasing homes later in life has extended mortgage payments into retirement-eligible years, an era once typically debt-free for previous generations. Commenting on these changes, Jiayi Xu, a senior economist at Realtor.com, noted that many older homeowners still have mortgages due to late-life home purchases. The percentage of these homeowners with remaining mortgage debt increased from 20.3% to 28.7%, meaning more than one in four elderly homeowners continue with monthly payments. Interestingly, the delay in property ownership has reflected a broader demographic shift, as the median age of first-time homebuyers reached a record high of 40 years. Owning a home outright was traditionally seen as a financial retirement goal, yet this aspiration has become less feasible for many. Regional disparities further illuminate this issue: Miami leads with the highest rate of mortgage-free homeownership (45.9%), closely followed by Buffalo (45.6%) and Pittsburgh (45.5%). By contrast, in Washington, DC, 73.2% of owner-occupied homes still have mortgages, with Denver and Raleigh also showing high rates of mortgage debt. This regional variation poses significant implications for the housing market. The historical trend of locking in low mortgage rates has led many homeowners to stay put amid rising borrowing costs, limiting housing supply. This mortgage rate lock-in effect, compounded by affordability challenges, strains prospective buyers’ choices. Conversely, mortgage-free homeowners retain flexibility, unencumbered by financial penalties associated with moving. This flexibility will likely play a crucial role as the nation’s aging population considers generational property transfer and relocation decisions, which could shape the housing market landscape significantly in the coming years.
About usyoo
Categories
Tags