News - Lucid Stock Defies Odds: Surges Despite Earnings Miss
Business Strategy
Lucid Stock Defies Odds: Surges Despite Earnings Miss
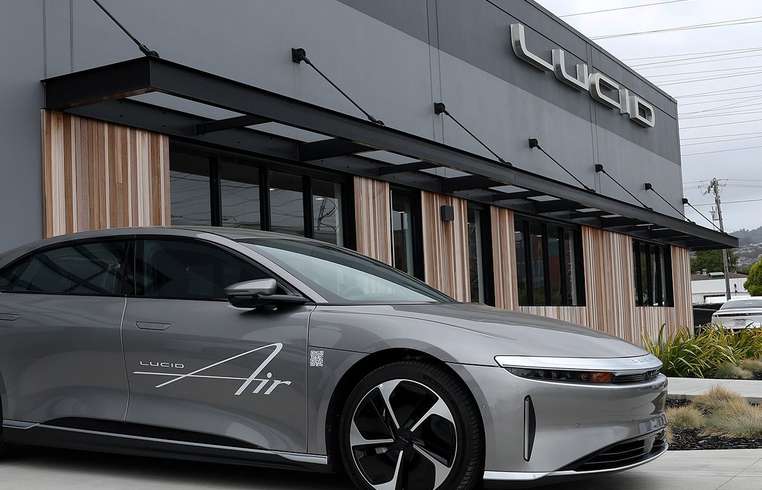
On Tuesday morning, Lucid Group's stock (LCID) experienced a remarkable surge, jumping 12% by 10 a.m. ET, marking its third consecutive day of increases, despite the company reporting earnings that fell below expectations. In anticipation of Lucid's Q3 earnings report, market analysts had predicted a challenging quarter, forecasting a loss of $2.25 per share against anticipated quarterly revenues exceeding $400 million. The actual financial disclosures showed a steeper loss of $2.30 per share with revenues only reaching $350 million. Despite these numbers, investor sentiment remained surprisingly unshaken. CEO Silvio Napoli attributed this to the company's strategic focus and improvements underway in their operational turnaround. Napoli emphasized that Lucid is executing "decisive actions to better align our manufacturing capacity with market demand, while actively reducing inventory and cutting operating expenses." While Lucid is not yet profitable nor generating a positive free cash flow, noteworthy developments include a 30% reduction in its cash burn rate from the previous quarter. The company has also injected fresh capital by raising $1.75 billion through stock sales, bolstering its cash position to above $930 million by the end of Q3. Looking forward, some concerns linger. Lucid's operations drained over $1 billion last quarter and nearly $4 billion since the year's start. However, current cash reserves are projected to cover operations for nearly another quarter, providing a buffer against immediate bankruptcy fears. Enhanced by approximately $2 billion in total liquidity, incorporating potential borrowings, Lucid may sustain itself for up to two additional quarters. Post this period, the outlook remains uncertain. While current optimism among investors fuels a bullish market view, some caution that without substantial improvement, Lucid's financial future remains precarious. The sustainability of its current market performance may thus be as risky as placing a new bet in an evolving market landscape.
About usyoo
Categories
Tags